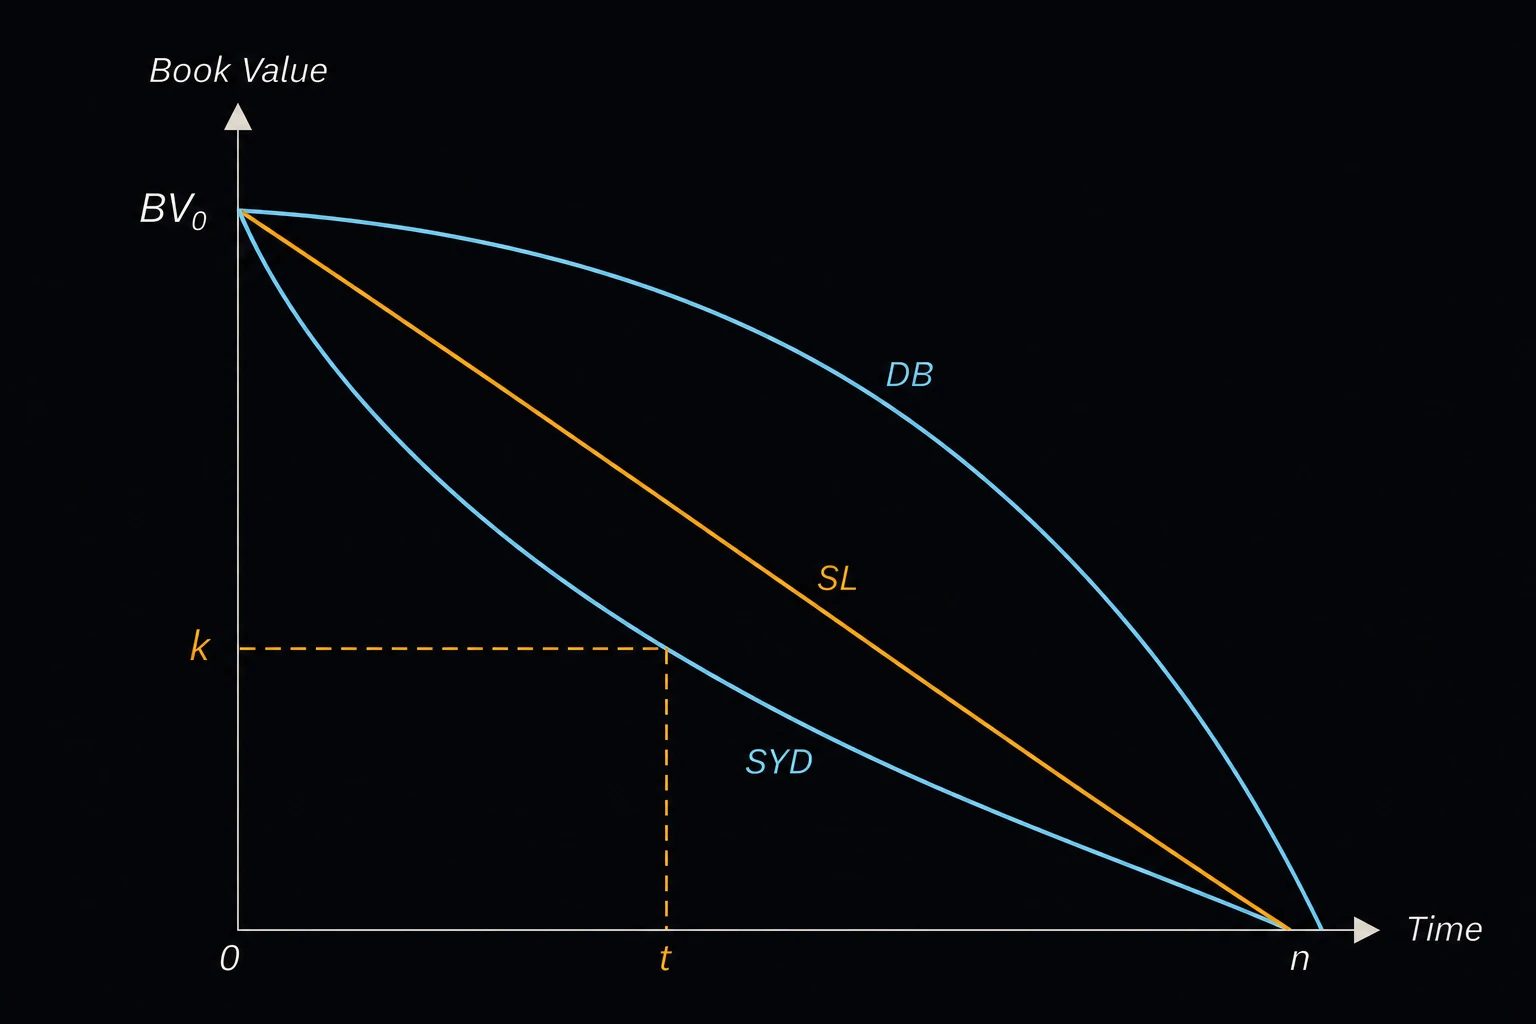
Depreciation Schedule
Gives the depreciation for any one year of an asset’s life, the depreciation accumulated to the end of that year and the book value left. It covers straight-line, 200 % and 150 % declining balance, sum-of-years’-digits and the U.S. tax method, MACRS GDS. Engineers and cost analysts use it to build after-tax cash flows for an economic study, or to check a book value before selling or replacing equipment.
The methods
SL: Dt = (B − S) / N SYD: Dt = (N − t + 1)/[N(N + 1)/2] · (B − S)
DB: Dt = d·BVt−1, d = 2/N or 1.5/N MACRS: Dt = rt·B
B is the depreciable basis (the cost, including installation and freight), S the estimated salvage value, N the useful life in years and t the year. BVt−1 is the book value at the end of the previous year, BVt = B − (D1 + … + Dt) [1], [2]. Declining balance never takes the book value below S. For MACRS, rt is the IRS rate for the year from Table A-1 of Publication 946 (half-year convention) [3]. MACRS ignores salvage and writes off the whole basis over the recovery period plus one year.
Choosing a method and common mistakes
- Use MACRS for U.S. federal tax. Pick the property class from the asset’s class life in Publication 946 [3]. The examples in the list are a guide only. The book methods (SL, DB, SYD) are for company accounts and textbook studies.
- Declining balance here does not switch to straight-line. It can leave the book value above the salvage value at the end of the life, so the full-schedule total can be less than B − S.
- The half-year convention gives MACRS one extra year: a 7-year property is depreciated over 8 tax years.
- Depreciation is not a cash flow. In an economic study it matters only through the taxes it saves.
- The page does not apply the mid-quarter convention, bonus depreciation or a Section 179 deduction.
Worked example
A shop buys a 250,000 CNC machining center, installed, and treats it as 7-year MACRS property. The tax planner needs the year-3 deduction and the tax book value after year 3.
- Choose Method MACRS GDS (half-year).
- Enter Depreciable Basis / Cost (B) 250000.
- Choose MACRS Property Class 7-year and enter Year of Interest 3.
- Press Solve. The Solution shows:
Depreciation in year 3: 43,725
Accumulated depreciation through year 3: 140,675
Book value at end of year 3: 109,325
Total depreciation over full schedule: 250,000
Recovery period: 7 years
MACRS rate in year 3: 17.49 %
Check: the first three 7-year rates are 14.29, 24.49 and 17.49 %, which add to 56.27 %. 0.5627 × 250,000 = 140,675, and 0.1749 × 250,000 = 43,725.